
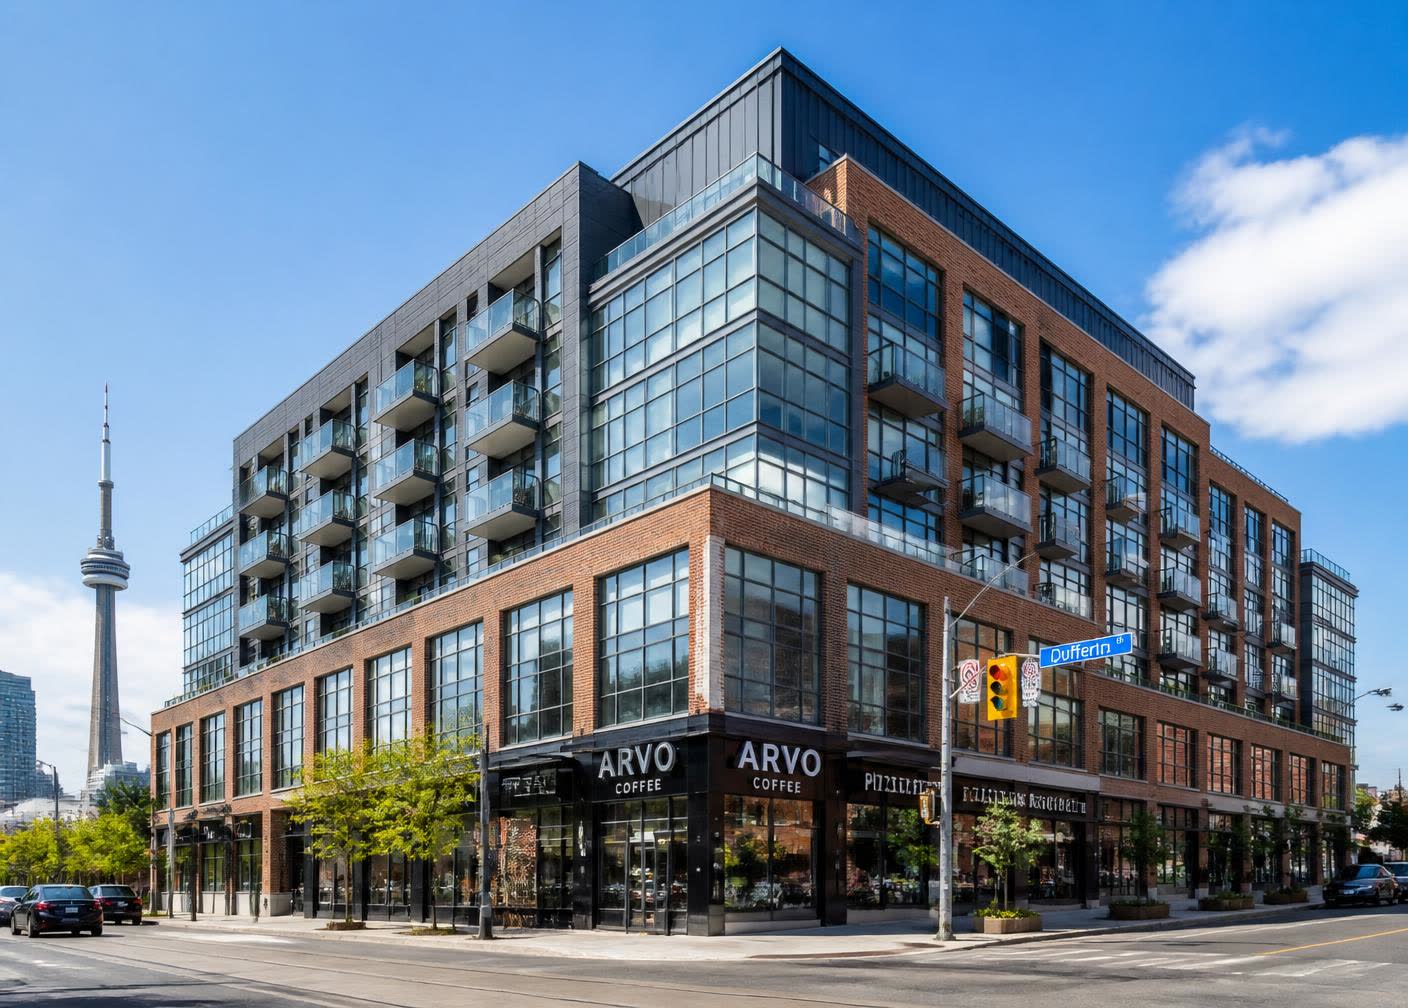
Commercial Mortgages Toronto
Commercial mortgages in Toronto for the buildings that pay you back. Our commercial desk arranges debt on income-producing and development real estate throughout Toronto and the GTA - from a six-unit walk-up to a full construction facility. We build the lender package, run the process, and negotiate the terms.
Asset classes we finance.
Multi-residential
Walk-ups, mid-rise rentals, and purpose-built apartment buildings, including CMHC-insured terms.
Retail & mixed-use
Main-street storefronts, plazas, and residential-over-retail buildings across the GTA.
Office
Professional suites, medical and dental offices, and small multi-tenant office buildings.
Industrial
Warehousing, light manufacturing, and flex space in Toronto's industrial corridors.
Land & development
Serviced and pre-development land, with terms structured around your approvals timeline.
Construction
Draw-based construction facilities and bridge debt through to stabilization or takeout.
The right instrument for the business plan.
Conventional term debt
First mortgages from Schedule A banks and credit unions for stabilized, cash-flowing assets.
CMHC-insured financing
Longer amortizations and higher leverage on qualifying multi-residential properties.
Bridge & transitional
Short-term capital while you reposition, lease up, or complete a value-add plan.
Private & second mortgages
Flexible capital when speed, story, or leverage matters more than the lowest cost of funds.
Commercial mortgages in Toronto - common questions.
What types of commercial mortgages are available in Toronto?
Toronto commercial mortgages cover multi-residential buildings, retail plazas, office properties, industrial and warehouse space, development land, and construction projects. Structures include conventional term debt, CMHC-insured loans, bridge financing, and private second mortgages.
How much down payment do I need for a commercial mortgage in Toronto?
Most commercial mortgages in Toronto require 25% to 35% down, depending on the property type, cash flow, and lender. CMHC-insured multi-residential deals can offer higher leverage, while land and construction deals typically require more equity.
Can I get a commercial mortgage with bad credit or non-traditional income?
Yes. Private commercial lenders in Toronto focus on the property's value and income rather than your personal credit. When the deal and the story make sense, approvals can come together quickly, even after a bank decline.
How long does it take to close a commercial mortgage in Toronto?
Conventional commercial mortgages typically close in 30 to 60 days, depending on appraisals, environmental reports, and rent roll review. Bridge and private commercial financing can close in as little as one to two weeks when the file is clean.
Send us the deal - we'll tell you where it fits.
Share the property, the rent roll or pro forma, and the capital you need. We'll come back with a realistic read on leverage, structure, and which lenders are the right audience.
Working on something time-sensitive? Text (647) 342-1355 for the fastest reply, or call the same number and ask for the commercial desk.